 by
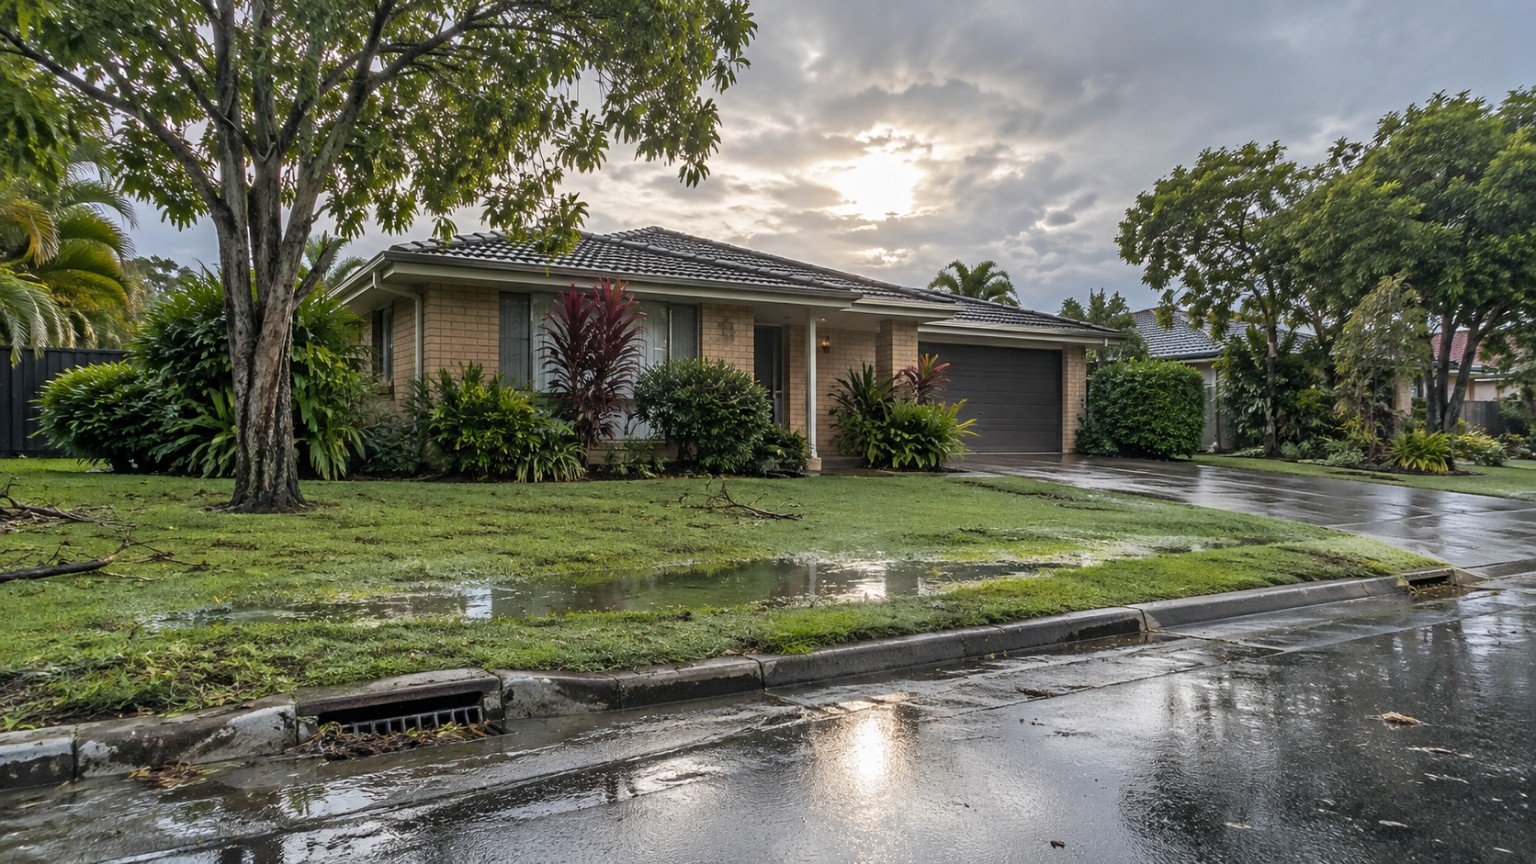
Most buyers treat insurance as a settlement-day formality — something to arrange once the keys are agreed on and finance is sorted. In a flood- or storm-exposed part of South East Queensland, that timing can be a mistake. If a property turns out to be difficult or expensive to insure, it can also turn out to be difficult to finance, and by the time that becomes clear it may be too late to walk away cleanly.
This article is not a guide to what home and contents insurance covers or how to pick a policy — Narevella already has a Beginner’s Guide to Home and Contents Insurance in Queensland for that. This article stays narrowly on one question: how to test insurability before you are locked into a contract.
Why insurance deserves a place in your contract conditions, not just your moving checklist
A finance condition and a building and pest condition are standard in most Queensland contracts. Insurability rarely gets the same treatment, even though it can be just as decisive. A property that is hard to insure is often also a property a lender is cautious about, because the lender’s own security is exposed to the same risk. Testing insurability early — while you still have a condition you can rely on — gives you a genuine exit point if the numbers do not work.
The pre-purchase research sequence
1. Run the correct hazard tool for the address
Start with the council’s own flood and hazard mapping tool for the specific address, not a general impression of the suburb. FloodWise is a Brisbane City Council tool only — Gold Coast, Ipswich, Logan, Redland and Moreton Bay each run their own mapping systems. If you are researching a canal or waterfront property on the Gold Coast, Narevella’s canal estates and waterfront flood research guide covers that council’s approach, and the Redlands bayside flood and storm tide guide covers storm tide research for that area.
2. Get an indicative quote from at least two insurers, for the specific address
A general estimate is not useful. Ask at least two insurers to quote against the actual address while you still hold a finance or building and pest condition. Ask each of them directly: is flood cover included, excluded, or optional as an add-on, and what excess applies specifically to flood?
3. Understand why quotes can differ sharply
Insurers price against their own hazard models, and those models do not necessarily match the council’s flood mapping. It is genuinely possible for a property outside a council-mapped flood area to attract a flood loading, and for a property inside a mapped area to be quoted more moderately than expected. This is one of the more useful, non-obvious things a buyer can learn before relying on a council map alone.
4. If the property is strata, ask what the body corporate policy covers
In a community titles scheme, the body corporate generally insures the building itself, while the lot owner is typically responsible for insuring contents and any improvements made to the lot. Rather than re-explain strata insurance mechanics here, see Narevella’s existing guide to body corporate checks for unit and townhouse buyers. The practical point for this article is simply to ask the question before you assume you are covered.
Storm and cyclone season timing
Insurers commonly apply waiting periods to new policies, and may restrict writing new business when a severe weather event is forecast or already under way. This is standard industry practice, though the exact length of any waiting period varies by insurer and by product, so this article will not state a specific figure — confirm the current position directly with the insurer you are dealing with. Narevella’s storm and cyclone season property preparation guide covers the broader seasonal picture for owners.
One practical implication follows from this: if you are buying in the lead-up to or during storm season, do not assume you can arrange cover at the last minute. Start the insurability check as soon as your offer is accepted, not in the final days before settlement.
What this means for your buying costs
An insurance quote is a genuine cost input, in the same category as the other figures you gather during your deposit, finance clauses and upfront buying costs research. If a property is going to carry a materially higher insurance cost than a comparable property elsewhere, that is worth knowing before you are contractually committed, not after.
The whole article in one line
Get a real insurance quote for the real address before your conditions expire. It costs nothing to ask and it can save you from being locked into a property that turns out to be uninsurable, or insurable only at a cost you had not budgeted for.
This article is general research information only. It does not consider your personal circumstances and is not financial, insurance or legal advice. Insurance availability, pricing and policy terms vary between insurers and change over time — always confirm current cover, exclusions and costs directly with insurers before relying on them.
Useful Narevella Reading
- Compare Suburbs — compare hazard exposure and research findings across different areas
- Find Property For Me
- Queensland Property Research Checklist
- Check My Property — get a structured research report on a specific address
Join The Discussion